T-12 Normalization: Build a Reviewable Adjustment Register
Normalize a T-12 with a traceable adjustment register. Recompute a fictional NOI bridge, separate pending assumptions and preserve the reported operating history.
T-12 Normalization: Build a Reviewable Adjustment Register
Normalize a T-12 by reproducing the reported operating results, then recording each proposed change in a separate adjustment register. Label whether the change corrects a classification, removes a supported nonrecurring item or introduces a forward assumption. Recalculate the bridge to adjusted NOI and keep unapproved assumptions out of the accepted case.
When an insurance renewal changes the expense assumption, use the insurance quote comparison exercise to keep the quote terms, adviser questions and scenario cost separate from the historical amount.
Keep the historical period intact
A T-12 describes a trailing twelve-month period. Before adjusting it, identify the start and end dates, accounting basis, income definitions and expense categories. Reconcile the totals to the supplied statement. If the file has missing months or an unexplained subtotal, record that problem before constructing a cleaner-looking result.
The multifamily underwriting walkthrough covers the full source-to-model sequence. This guide focuses on the adjustment record: how another analyst can reproduce the change from reported operations to the proposed acquisition case.
Keep the original statement and a read-only transcription. An AI assistant can help organize line items, but it should not replace a missing value with zero or mix a new insurance quote into the historical column. A reviewer needs to see both the supplied value and the proposed change.
Give each adjustment a reason and a status
Use a register with the line item, historical amount, proposed change, direction of the NOI effect, basis, source location, effective period, reviewer and status. Write amounts using a consistent convention. In the exercise below, positive expense changes increase expenses and reduce NOI.
Separate three kinds of work. A classification correction changes where an observed item appears. A supported nonrecurring adjustment proposes removing an item from a recurring case. A forward assumption substitutes a future amount that the historical statement cannot establish. Do not describe all three as verified historical performance.
For example, a seller's tax payment does not settle a buyer's future tax liability. Obtain support for the relevant jurisdiction and transaction; do not apply a universal reassessment rule. An insurance budget also needs its own basis and period. A proposed figure can remain provisional while the rest of the review proceeds.
The OCC's Commercial Real Estate Lending handbook provides banking-supervision context for evaluating property cash flow. It does not turn a buyer's assumptions into a standardized acquisition model. Follow the definitions required for your actual investment and financing analysis.
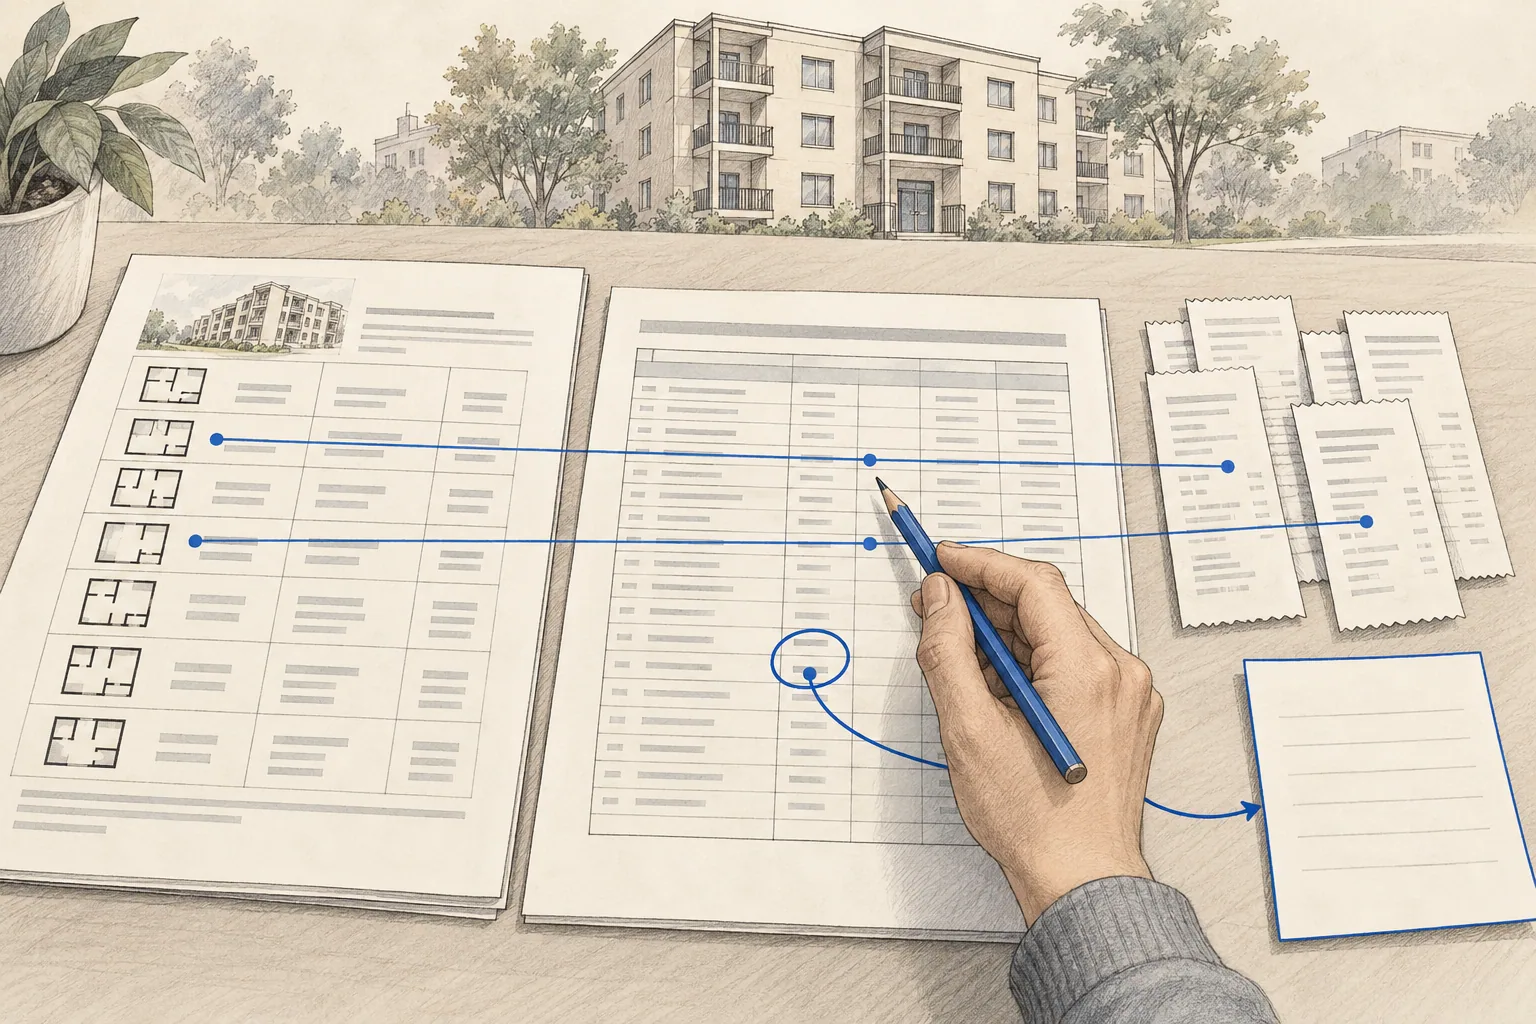
Worked example: reported NOI of $408,000
All amounts and source records below are invented teaching data. They are not a property valuation, market forecast, client outcome or tax estimate. The fictional statement covers January through December 2025 and uses the simplified categories shown here.
| Historical line | Annual amount |
|---|---|
| Rental income | $600,000 |
| Other operating income | $24,000 |
| Total operating income | $624,000 |
| Property taxes | $90,000 |
| Insurance | $24,000 |
| Repairs | $36,000 |
| Management | $30,000 |
| Utilities | $24,000 |
| Administration | $12,000 |
| Total operating expenses | $216,000 |
| Reported NOI | $408,000 |
This simplified statement already reports rental income after its applicable collection adjustments. The exercise does not deduct vacancy or concessions again. In a real statement, check the source definition rather than relying on that label.
Bridge accepted changes separately from the open tax scenario
| Proposed change | Income change | Expense change | NOI effect | Exercise status |
|---|---|---|---|---|
| Remove fictional nonrecurring settlement receipt from other income | -$6,000 | $0 | -$6,000 | Accepted for the recurring case |
| Replace insurance expense using the supplied fictional renewal quote | $0 | +$6,000 | -$6,000 | Accepted forward assumption |
| Remove documented fictional one-off cleanup from repairs | $0 | -$8,000 | +$8,000 | Accepted for this exercise only |
| Increase tax expense using an unverified buyer estimate | $0 | +$18,000 | -$18,000 | Pending; separate scenario |
The accepted bridge is $408,000 - $6,000 - $6,000 + $8,000 = $404,000. It has $618,000 of income and $214,000 of operating expenses. The cleanup adjustment assumes the supplied record establishes a one-off event and that the remaining expense provision is adequate within this fictional case. A real reviewer would need to assess continuing maintenance requirements.
If the pending tax estimate is included in a separate scenario, expenses become $232,000 and NOI becomes $386,000. Label that scenario as including the unverified tax assumption. Do not promote it to the accepted case through a more polished narrative.
The point of retaining both outputs is practical: the committee can see which figure changes if the tax support arrives. It does not have to reconstruct the model from a paragraph about "normalized NOI."
Download the T-12 adjustment practice pack. The CSV worksheets contain the historical statement, fictional supporting notes, adjustments, both calculation bridges and an answer key. The amounts can be recomputed independently; no live property data is included.
State the treatment of reserves and debt service
Do not assume every model uses the same definition of net cash flow. Fannie Mae's Multifamily Guide, Part II section 203.01, subtracts replacement-reserve expense from underwritten NOI in its underwritten net cash flow calculation. That is a specific lending definition, not a reason to move every capital item into operating expenses.
For illustration, a separate fictional $12,000 reserve would reduce the accepted case's $404,000 NOI to $392,000 before debt service under that simplified treatment. The pending-tax scenario would produce $374,000 before debt service. These are labeled outputs with different assumptions; neither is a promised return or an approved lender calculation.
Keep capital expenditures, financing costs and debt service visibly separate unless the specified model calls for a particular treatment. The reviewer should be able to follow the calculation from the source without guessing what a subtotal includes.
Ask AI for a register, then verify it
Try the practice packet with this instruction: "Reproduce the historical totals first. For every proposed adjustment, identify the affected line, income or expense change, NOI effect, source file and status. Calculate an accepted case excluding pending items and a separate scenario including the pending tax estimate. Do not invent a quote, reviewer approval or missing statement value."
Check the arithmetic in your workbook or another deterministic calculation. Open the supporting document for each material change. A correct final total can hide offsetting errors, so verify the individual signs as well as the sum. Inspect material values that received no warning, too.
Repeat the exercise with the tax estimate removed. The accepted case should remain $404,000, and the workflow should explain that the tax scenario lacks an input. It should not silently substitute the historical tax amount while retaining the scenario's old label.
Carry the register into the next model revision
Keep accepted changes, provisional changes and superseded assumptions in the same review history. When a better quote arrives, preserve the earlier input and record why the replacement was accepted. Then refresh the affected calculations before updating any memo.
The underwriting model-builder pack provides a broader structure for organizing that handoff. The public IC memo walkthrough shows the downstream document workflow. A useful automation leaves the analyst able to challenge an assumption without losing the operating history beneath it.
Work through the next review
After accepting the adjustment register, use the Excel formula-check exercise to verify that the approved inputs still drive NOI and coverage when one assumption changes.
Frequently asked questions
What is the difference between reported and adjusted NOI?
Reported NOI reflects the supplied historical statement under its stated definitions. Adjusted NOI incorporates separately identified corrections or assumptions. Preserve both and explain each change.
Should a pending tax estimate enter the accepted case?
No. Keep unsupported estimates pending and show their effect in a separately labeled scenario until the appropriate reviewer accepts the supported assumption.
Do replacement reserves belong in NOI?
Definitions depend on the model. This exercise keeps reserves outside operating expenses and shows a separate deduction after NOI. State the actual financing or investment definition you are using.
Has an AI model passed this practice exercise?
No measured model result is claimed. The packet supplies synthetic inputs and an answer key for your own reproducible evaluation.
Continue the workflow
For the next step, use rent roll reconciliation worked example, how to underwrite RUBS income, hotel statements under the USALI 12th edition.
Related Articles
Multifamily Renovation Tracking: Budget, Rent and Collections
Track multifamily renovations from approved scope and cost to signed rent and collections. Keep incomplete units visible with a fictional unit-level worksheet.
CRE Insurance Quote Comparison: Check the Coverage and Cost
Compare CRE insurance quotes by coverage, limits, deductibles and total cost before changing the underwriting case. Includes a fictional quote worksheet.
Commercial Lease Rollover Schedule: A Checked Example
Build a commercial lease rollover schedule with an as-of date, checked area and rent totals, and options kept separate. Includes a fictional CSV exercise.