

How to Underwrite a Multifamily Deal With AI: A Practical Walkthrough
Underwrite a multifamily deal with AI using a reconciled rent roll and T-12, then separate observed results, market estimates and buyer scenario assumptions.
How to Underwrite a Multifamily Deal With AI: A Practical Walkthrough
To underwrite a multifamily deal with AI, extract the rent roll, T-12 and offering memorandum, reconcile the units and periods, rebuild reported NOI, then create a separate buyer case. Label each input as observed, estimated or proposed. The analyst verifies sources and approves adjustments.
You underwrite a multifamily deal with AI by feeding it the rent roll, T-12, and offering memorandum, then letting it extract the line items, normalize them, and flag what it cannot verify. The AI populates the model and surfaces risk. You, the investor, still judge the deal and decide.
Below is a proposed first-pass multifamily workflow, with a reviewer responsible for accepting each stage before the figures move into a decision.
Before accepting a replacement insurance expense, work through the quote comparison and NOI bridge. A lower premium does not establish equivalent coverage.
After acquisition, reconcile the business-plan assumption with the unit-level renovation and collections worksheet. Keep target rent, signed rent and cash collected in separate fields.
The most expensive hour in acquisitions
A first-pass underwrite starts with the offering memorandum, rent roll, and T-12. Extract and reconcile the source figures before changing assumptions. Measure the time your team spends correcting and reviewing the output to decide whether the workflow helps.
The workflow, stage by stage
Here is the map. Each stage hands the mechanical work to the model and keeps the judgment with you.
| Underwriting stage | What the AI does | What you still own |
|---|---|---|
| Ingestion | Reads the rent roll, T-12, and offering memorandum and pulls the line items into one clean structure | Confirming the documents are complete, current, and the ones you actually received |
| Rent roll normalization | Standardizes unit types and flags month-to-month leases, near-term expirations, and concessions | Deciding which flags actually change the thesis |
| In-place NOI | Reproduces historical NOI from the T-12, then builds a separate buyer-adjusted case from approved assumptions | Setting the assumptions the rebuild runs on |
| Market context | Assembles comparable rents and a rent-gap view from your own data sources | Judging which comps are genuinely comparable |
| Pro forma and sensitivity | Populates a multi-year pro forma and a sensitivity view from the structured inputs | The cap-rate and growth assumptions, and the pursue-or-pass call |
Ingestion and normalization
The first bottleneck in multifamily underwriting is always the rent roll. Sellers hand it over in whatever shape it happens to be in: a clean export sometimes, a scanned PDF that has survived three ownership transfers more often. The model extracts it into a consistent table and, more importantly, flags the things that hide behind a headline occupancy number: units on month-to-month leases, expirations clustering in the near term, and concessions quietly inflating gross income. If you are still comparing tools for this layer, our guide to the best multifamily underwriting software lays out the field.
Rebuild an honest NOI
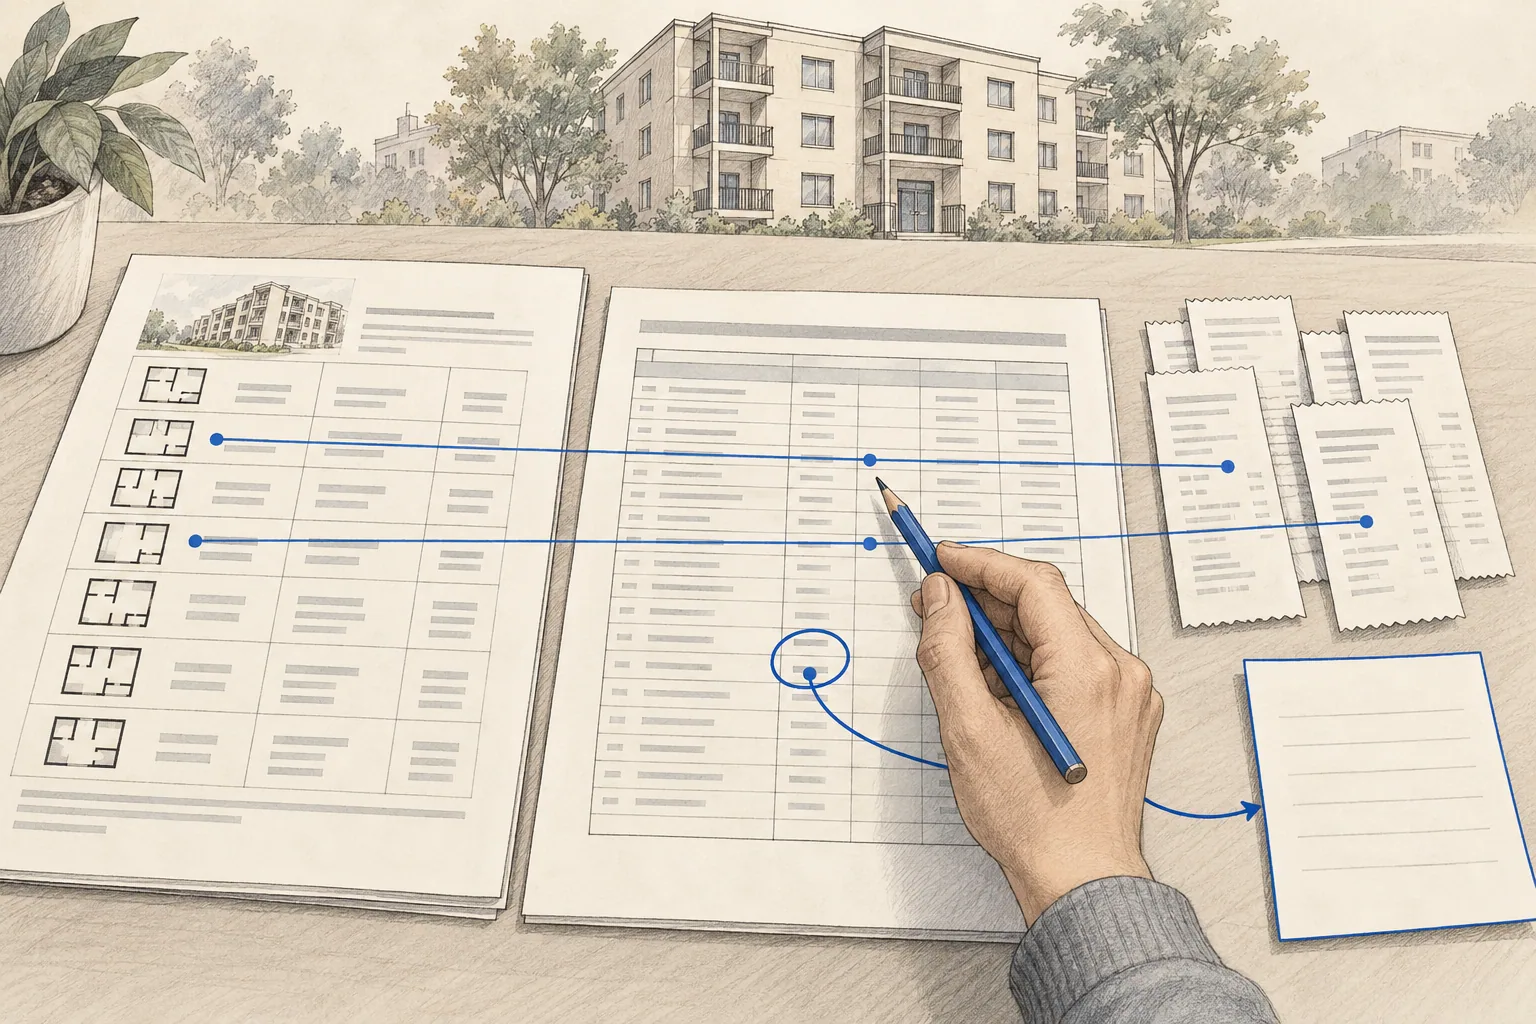
First reproduce the seller’s historical T-12 without changing the assumptions. Reconcile the period, income categories, concessions, vacancy, bad debt, and operating expenses. Keep debt service and capital expenditures separate from operating expenses.
Then build a distinct buyer-adjusted case. A possible tax reassessment, a new insurance quote, or a management-fee adjustment belongs in that case with its source and reviewer approval. Do not label the adjusted result “historical in-place NOI,” and do not deduct concessions twice if reported income is already net of them.
Worked example: actual NOI versus a buyer-adjusted case
Illustrative figures, not a client result: a T-12 shows $600,000 of collected rental income, already net of $12,000 in concessions, plus $20,000 of other operating income and $260,000 of operating expenses. Historical NOI is $360,000. Deducting the concessions again would incorrectly reduce it to $348,000.
If the reviewer then approves a $20,000 annual tax increase and a $5,000 insurance increase, the buyer-adjusted NOI is $335,000. Preserve both cases. At an assumed $250,000 of annual debt service, DSCR is 1.44x for historical NOI and 1.34x for the adjusted case. These inputs are an arithmetic example, not a forecast or lending recommendation.
- Link historical figures to their T-12 rows.
- Label tax and insurance changes as assumptions until supported.
- Recompute NOI and DSCR in the workbook rather than trusting prose.
- Keep the reviewer and approval date beside each adjustment.
Market context and the pro forma
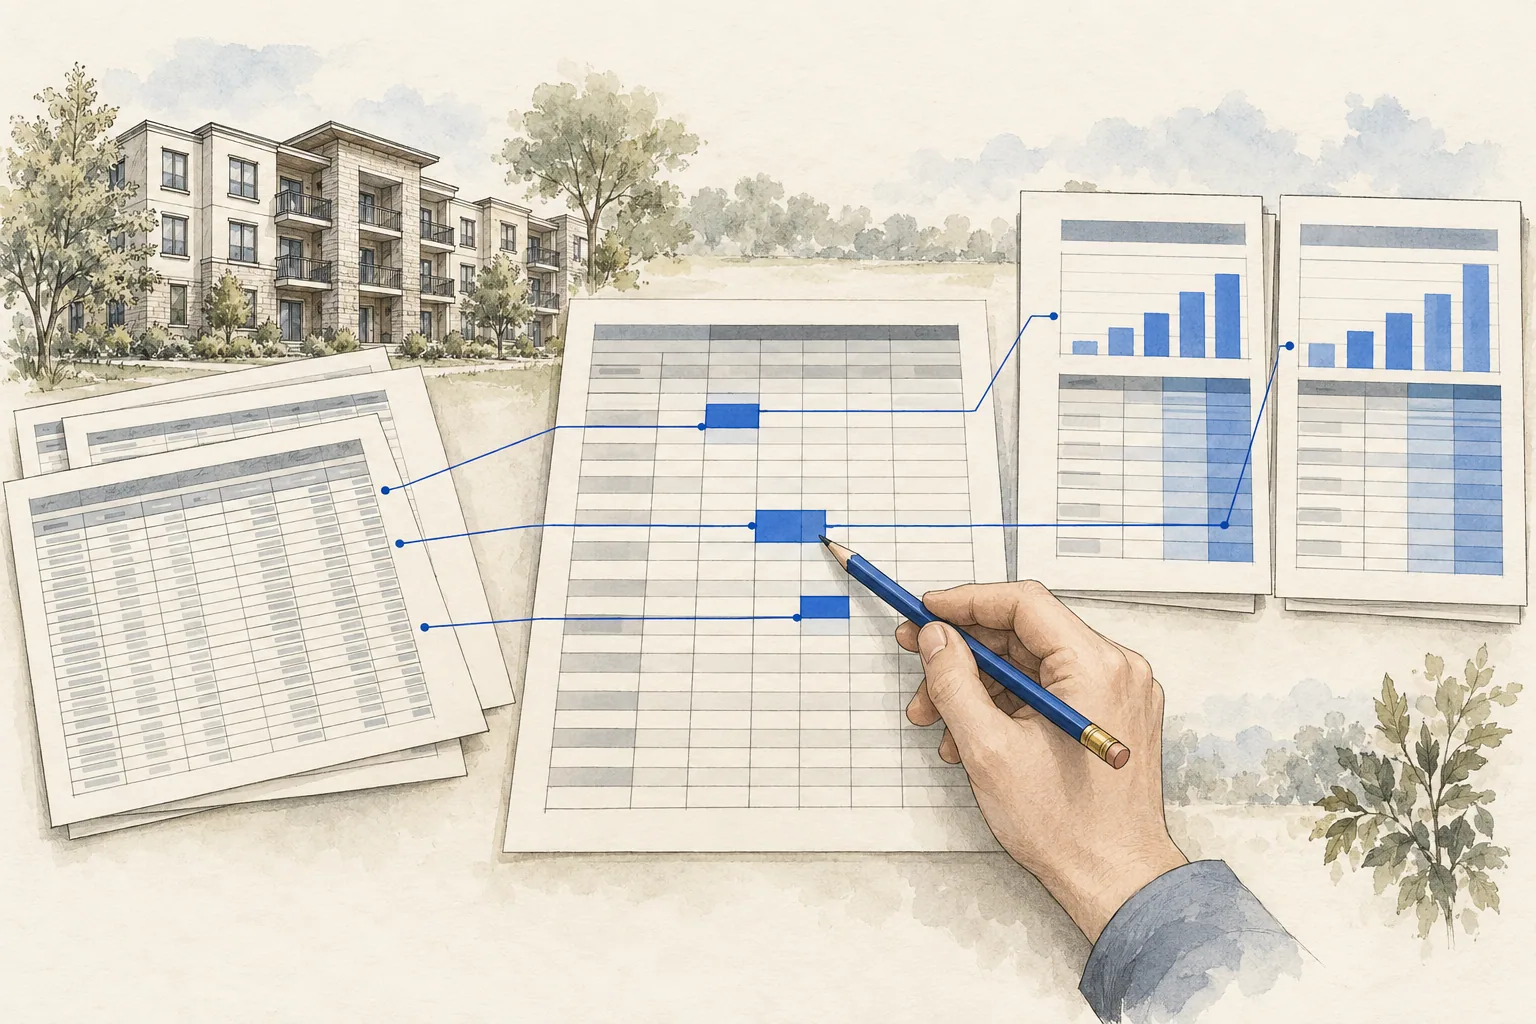
Use your approved comp sources to assemble a market view, then populate scenarios in the model. Review which comps are comparable, record the cap-rate and growth assumptions, and check how changes flow through the formulas.
The rule that makes it trustworthy
Here is the part people skip, and it is the one that turns a handy tool into a real liability. A model can fill an empty cell with a plausible but unsupported number, and in an underwrite a made-up rent is worse than a blank one, because it looks finished. So you hand the model one hard rule: use only what is in these documents, and where a number is missing, write a flag that names exactly what to go verify. Never a guess. Check that the output obeys the rule; a prompt alone does not guarantee it. Every material figure needs a source or an explicit diligence flag before review.
Where this fits your team
None of this replaces your analysts. It moves their hours off data entry and onto judgment, which is the only place their time was ever worth much. A custom workflow also does not start as a giant platform build: scope and cost depend on the documents, integrations, model, and review process. If you want to see where an AI-assisted process fits your portfolio strategy, start with how we work with investment teams, or compare the wider field in our guide to the best AI tools for CRE underwriting.
Put the review into practice
For a row-by-row check before the NOI model, use the Claude rent-roll reconciliation example. It includes a duplicate row, a concession and an unresolved historical comparison, with an answer key that makes errors visible.
The assumption ledger: observed, estimated and proposed
Preserve the reported operating case before building the buyer case. An estimate must not overwrite an observed number. Record the source and date for a market assumption and the approver for a proposed scenario.
| Input | Observed file | Market estimate | Buyer scenario |
|---|---|---|---|
| In-place rent | Rent roll by unit and date | Comparable rents with source date | Approved leasing plan |
| Concessions | Ledger and lease support | Comp support if available | Explicit future assumption |
| Real estate tax | Current bill | Reviewed reassessment estimate | Sensitivity case |
| Insurance | Policy or invoice | Dated quote | Approved coverage assumptions |
| Capital work | Known scope and invoices | Contractor pricing | Phasing and contingency |
| Exit cap rate | Not historical property income | Dated comparable evidence | Approved exit assumption |
For an entirely fictional valuation check, NOI of $500,000 at 5% gives $10,000,000; a buyer case of $540,000 at the same 5% gives $10,800,000. The $800,000 difference comes from the proposed $40,000 NOI adjustment, not from observed performance. Neither value is a forecast.
Apply the same separation to RUBS income. A market survey is context; it does not establish that a particular property is comparable.
Frequently asked questions
How do you underwrite a multifamily deal with AI?
Use AI to extract and structure the rent roll, T-12, and offering memorandum, then have an analyst reconcile the figures. Reproduce historical NOI before building a separate adjusted case. Verify sources, assumptions, and formulas before using the model in an investment decision.
What does the AI actually do, and what does the human still own?
AI can help with extraction, formatting, comparison, and draft narrative. A reviewer verifies the source figures, approves adjustments, selects comparable properties, and owns the final decision. Measure corrections and review effort on your documents before relying on the workflow.
Will AI just make up rents and cap rates when a number is missing?
It can. Require source references and missing-data flags, then verify those outputs with reconciliation checks and human review. A prompt is a useful instruction, not an accuracy guarantee.
How much does an AI multifamily underwriting workflow cost to build?
Cost depends on document formats, model complexity, integrations, and the review process. Scope a representative deal before agreeing a price or savings target.
Want this workflow running inside your deal process?
We scope document extraction, reconciliation, and review for acquisition teams. The acceptance check is explicit: each material figure must have a verifiable source or an unresolved flag before the reviewer approves it.
Review the underwriting workflowRelated: the full AI-for-multifamily playbook.
For the bridge between reported and adjusted NOI, work through the T-12 adjustment register exercise and keep pending assumptions out of the accepted case.
Continue the workflow
For the next step, use multifamily acquisition review, rent-to-receipts exception bridge.
Check the restriction agreement for affordable units
Before using a rent-growth assumption on a restricted property, read the land use restriction agreement into a unit register. Match the recorded terms and amendments to unit designations, retain source references and leave unresolved rent-authority questions with the responsible reviewer.
Review the tax change separately
The tax reassessment underwriting exercise shows a separate annual NOI bridge and supplemental-bill reconciliation. Preserve historical expense and the accepted buyer case as separate records.
Related Articles
Multifamily Renovation Tracking: Budget, Rent and Collections
Track multifamily renovations from approved scope and cost to signed rent and collections. Keep incomplete units visible with a fictional unit-level worksheet.
CRE Insurance Quote Comparison: Check the Coverage and Cost
Compare CRE insurance quotes by coverage, limits, deductibles and total cost before changing the underwriting case. Includes a fictional quote worksheet.
Commercial Lease Rollover Schedule: A Checked Example
Build a commercial lease rollover schedule with an as-of date, checked area and rent totals, and options kept separate. Includes a fictional CSV exercise.