Components and shared obligations

Mixed-use acquisition review: reconcile component obligations

Mixed-use research should preserve the economics and obligations of each component before combining the property. Apartments, retail, offices and parking may share a structure while using different leases, meters and governance arrangements. AI can help build a component map and allocation record, making visible where a consolidated operating statement hides dependencies or counts a shared cost twice.

NextAutomation editorial research method. Public sources establish the framework; the worksheet example is fictional and no property has been verified.

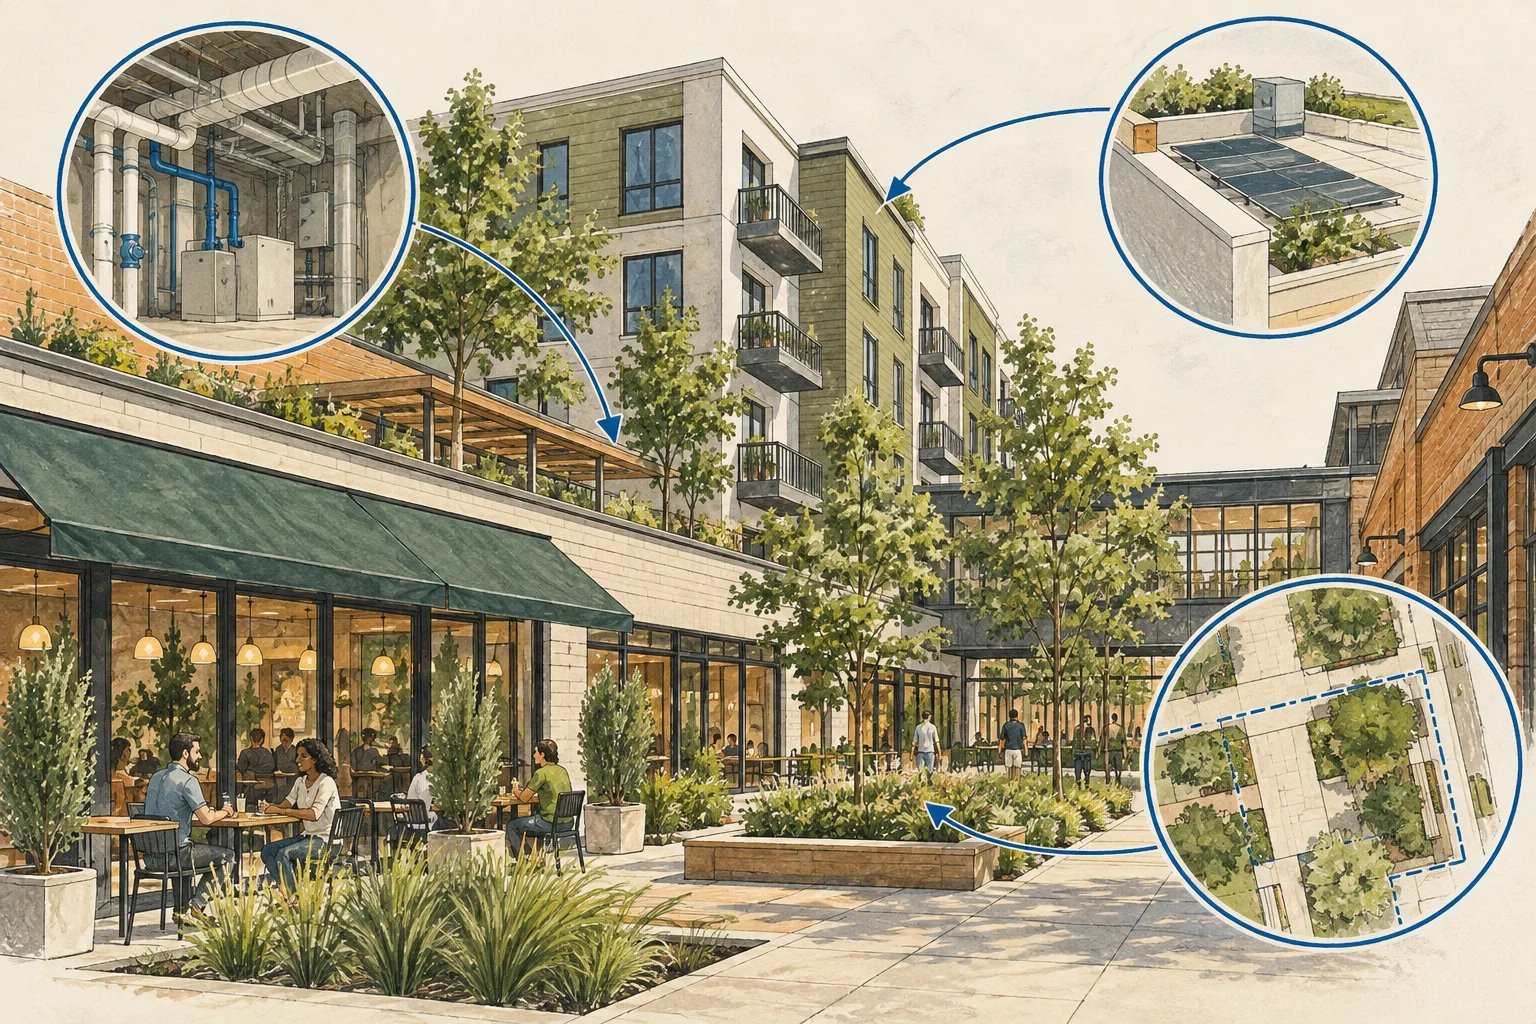
Conceptual illustration of mixed-use component income, common systems and governance

What changes the decision

Read the operating model before the headline

01

A category is not an allocation method

ENERGY STAR lists mixed use among its property categories for benchmarking. That provides a useful reminder that building use can be composite, but it does not determine legal boundaries or cost shares. Establish each component’s premises, operating hours and systems from the actual records before choosing how information should be combined.

Source 1
02

Shared infrastructure creates dependencies

Loading access, fire systems, ventilation, roofs and utility service can support more than one component. Identify who controls each system, who can authorize work and who bears the cost. A tenant’s proposed alteration may affect another use even when its own premises are clearly defined. Keep those interfaces visible in the review rather than burying them in general expenses.

03

Governance can sit outside the lease

Reciprocal easements, condominium documents, association budgets and maintenance agreements can govern rights or costs that a rent roll omits. Request the full document chain. An ownership percentage is not automatically the expense allocation, and one party’s budget does not establish another party’s consent. AI should preserve conflicting provisions for a qualified reviewer.

Keep these separate

Three distinctions to preserve in the file

Evidence or situationWhat it tells youWhat to establish next
Component incomeDescribes revenue from a particular useKeep its lease or operating basis separate before consolidating with other components.
Shared system expenseSupports several uses or parcelsIdentify control, allocation basis and any reimbursement agreement.
Consolidated property statementPresents a combined accounting viewReconcile component totals, intercompany entries and shared costs without double counting.
Conceptual illustration of mixed-use component income, common systems and governance

A practical review sequence

Build a file another reviewer can follow

Use the sequence below to turn the initial description into specific document requests. Preserve contradictory records instead of choosing the more favorable version.

  1. Map the components and boundaries

    List each use, floor or parcel, controlling entity and agreement. Connect component names used in plans to names used in accounting. Flag areas with ambiguous ownership or control. A colorful stacking plan is an orientation tool, not proof of legal boundaries or a right to alter the building.

  2. Trace each revenue stream

    Request the leases or operating agreements underlying apartment rent, retail rent, parking income and other receipts. Record whether the amount represents gross operations, rent or a management fee. AI can sort descriptions but should not treat differently structured revenue streams as economically equivalent simply because they appear in one statement.

  3. Reconcile common costs

    Ask for meters, service contracts, association accounts and allocation schedules. Follow a shared expense from invoice through allocation to reimbursement. Preserve unallocated and disputed items. If a cost appears in both a component statement and the consolidated total, request the accounting bridge before using either figure in an operating model.

  4. Create the governance handoff

    Identify the documents and consents needed for the proposed action, such as a tenant replacement, system upgrade or circulation change. Give counsel, engineer and accountant the same component map. Export unresolved rights and cost questions together so a solution in one component does not create an overlooked obligation elsewhere.

Questions that arise during review

Resolve the ambiguity before the model

Can mixed use be valued with one blended assumption?

A later valuation may consolidate components, but the evidence should first preserve their different leases, operations and costs. This guide prepares that record. It does not choose valuation methods or assume one component’s economics represent the entire property.

Is a shared meter a reason to stop?

It is a reason to request the allocation and responsibility records. Document how costs are measured, assigned and reconciled, and which party can change the arrangement. The worksheet should show an unresolved allocation rather than inventing a percentage.

What should AI flag in the accounts?

Duplicate expense descriptions, inconsistent component names, unexplained transfers and amounts that lack an allocation reference are useful candidates for review. A flagged entry is not proof of an error; the accountant should explain the transaction and preserve the supporting documents.

From the page to your next task

Start with the useful output.

Component income and shared-cost allocation bridge

Build an editable component income and shared-cost allocation bridge, retain document references and open decisions, then export your team's working file.

Scope: mixed-use component income, common systems and governance

Bring
An optional file nickname Status, observations and document references for the four evidence items; unknown is acceptable
Leave with
Component income and shared-cost allocation bridge with editable, expandable records and document locators Two fictional worked rows showing mismatches and decisions to review CSV and readable text exports with row provenance, method sources and edition A separate document-request companion with suggested reviewers

Edition 2026-09-30.1

Evidence and scope

Follow each claim to its source.

Commercial Real Estate Lending, Comptroller’s Handbook, version 2.0

Office of the Comptroller of the Currency · Checked 2026-09-30

March 2022 supervisory handbook; lease review, property income, re-leasing costs and property-type distinctions.

  • Bank supervisory guidance, not a property appraisal, current market survey or universal financing standard. No handbook percentage is adopted as a deal assumption.
Open original source ↗
Property Types in Portfolio Manager

ENERGY STAR · Checked 2026-09-30

Building-use categories for energy benchmarking, including mixed use, medical office and laboratories.

  • Benchmarking categories are not zoning classifications, licenses or certifications that a proposed use fits a building.
Open original source ↗