Rhode Island / Providence property example

Providence mixed-use records: match parcel and premises

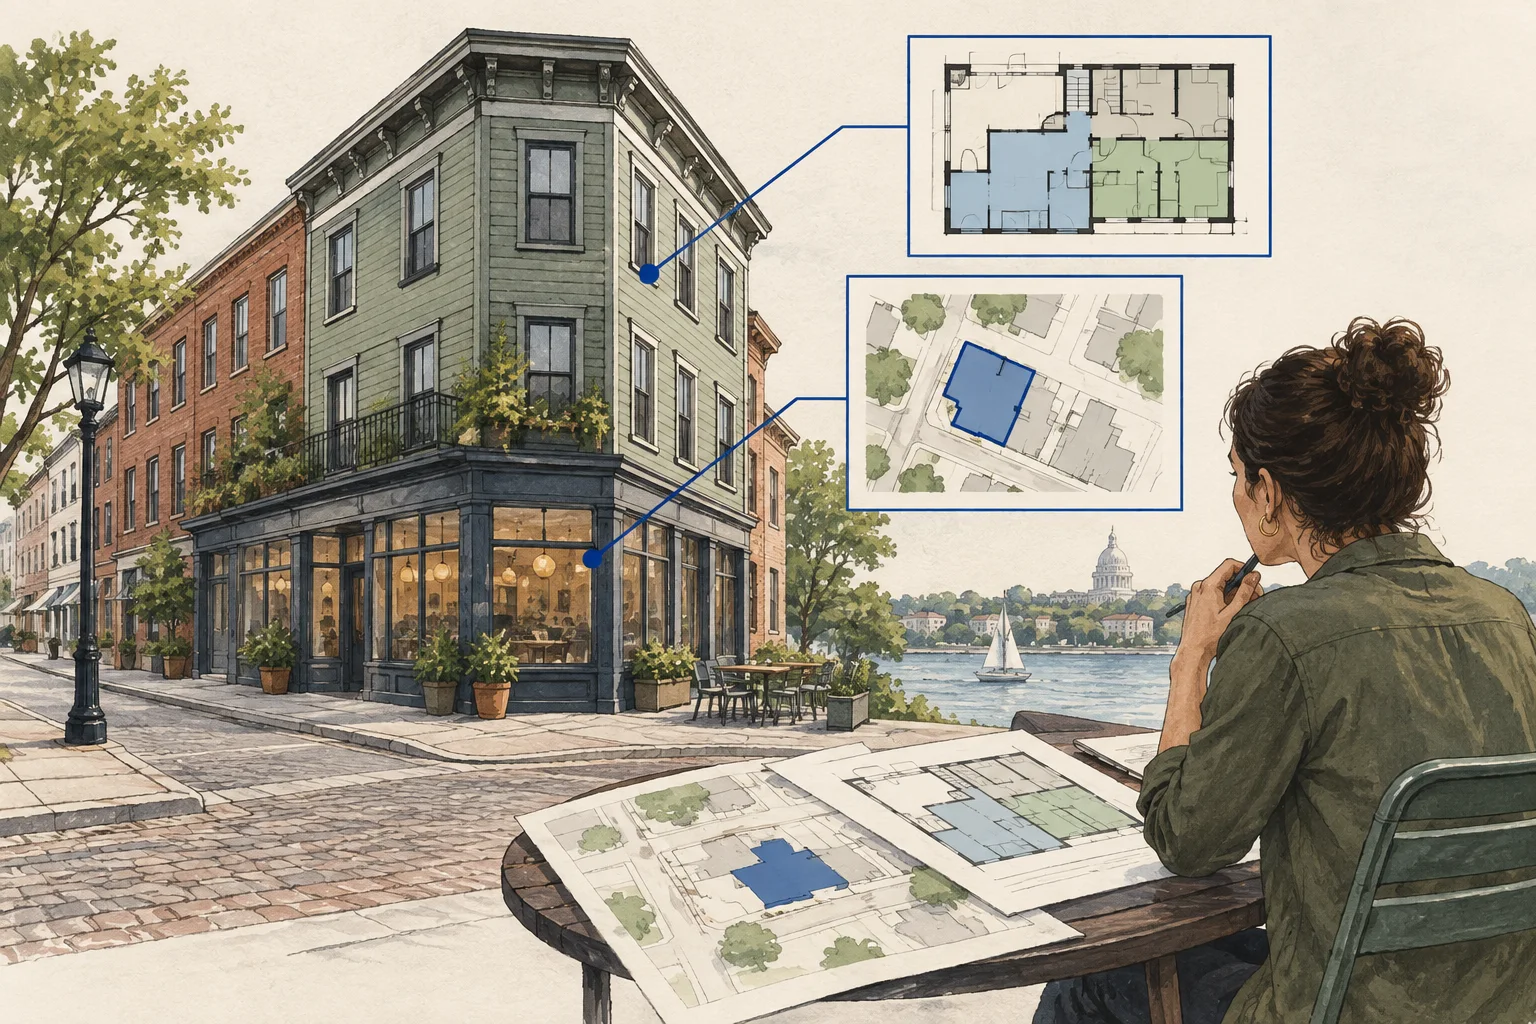
A compact Rhode Island mixed-use property can contain several different income and operating units inside one assessor record. Build a premises schedule before comparing the deal with a pure retail or apartment asset. Use the public property record as an identity reference, then reconcile commercial space, residential units, common systems and the costs each component actually carries.

Providence’s assessor resources are the municipal example. This is an editorial reconciliation method, not a statewide unit inventory or a property-specific legal-use determination.

Conceptual illustration of documents and decisions for Rhode Island commercial property research

What changes the decision

Rhode Island mixed-use property: reconcile the parcel, the premises and the income

01

The assessment record is an identity starting point

Providence’s Tax Assessor describes maintaining property information including ownership changes, building structures, uses and legal descriptions, and provides a property-lookup route. That makes the record useful for a consistent starting identity. It does not replace the leases, unit schedule or professional review needed to describe how a mixed-use building currently operates.

Source 1
02

Count premises before combining income

Create separate entries for each commercial premises and residential unit, preserving the labels used in the source documents. Record vacant, combined or unavailable areas explicitly. Then reconcile leases and operating records to those entries. This prevents a shop plus apartments from becoming a single unexplained unit count or an income total with no traceable components.

03

Shared systems can hide the real expense allocation

Ask which components share heat, water, access, insurance and maintenance, and how the owner allocates those costs. Retain the lease terms and billing evidence behind the allocation. A retail tenant’s reimbursement arrangement may differ from the residential operating costs, so an apparently simple building-level expense ratio deserves a premises-level explanation.

Read the records together

Evidence and its investment use

EvidenceWhat it establishesNext decision
Assessor property recordThe municipal property identity and supplied descriptive fields.Reconcile the record with the current building and premises schedule.
Commercial and residential schedulesThe owner’s description of rentable premises and income.Explain combined, vacant or differently labelled spaces.
Shared-system and lease evidenceThe basis for cost responsibility and reimbursement.Separate operating expenses by documented treatment.
Conceptual illustration of the Rhode Island research workflow

Put it to work

Mixed-use premises and expense bridge

The worksheet creates a mixed-use reconciliation file. It is intended to expose the small classification and allocation gaps that can distort an otherwise plausible acquisition summary.

  1. Establish the property reference

    Use the municipality’s official assessor path to record the property identity and the date of the information used. In Providence, preserve the descriptive fields as reported. Keep the source record intact when the current owner’s layout differs, and create a separate discrepancy entry rather than editing away the difference.

    Source 1
  2. Draw a premises schedule

    Request a dated floor plan, residential unit list and commercial rent roll. Match each income line to a physical premises and record shared areas separately. Ask the owner to resolve mismatched labels, merged spaces and uses that appear in one document but not another.

  3. Trace shared costs to documents

    Request the relevant lease clauses, bills and management allocation schedules. Identify which costs are paid directly, reimbursed or retained by the owner. Ask the property accountant to explain unsupported allocations so the buyer can compare consistent operating categories without inventing an expense split.

  4. Prepare the acquisition comparison

    Summarize the commercial and residential components separately before presenting the combined building. State unresolved premises or expense questions and assign a reviewer. Export the kit as the document request sheet, with any legal-use or physical-system interpretations left to the appropriate local and technical professionals.

Before the next conversation

Questions this review should answer

Can one assessor use label describe the whole investment?

It may be useful for classification, but the acquisition needs the current premises and income composition. Preserve the assessor label and build the operating schedule beside it. Differences should prompt a document request rather than an automatic conclusion that the municipal record or seller schedule is wrong.

Should shared expenses be split by floor area?

Use the documented lease and operating arrangements first. A floor-area split may be a proposed analytical assumption, but it is not a fact simply because measurements are available. Label any assumption and have the property accountant explain its effect before relying on the combined operating statement.

What can an AI assistant organize here?

AI can match rent-roll lines to plan labels, flag unmatched premises and extract reimbursement clauses for review. It should retain original descriptions and document locations. The owner, accountant and appropriate professionals must resolve whether spaces, allocations and represented uses are correctly described.

From the page to your next task

Start with the useful output.

Premises-to-income-and-expense bridge

Build an editable premises-to-income-and-expense bridge, retain document references and open decisions, then export your team's working file.

Scope: Mixed-use reconciliation

Bring
A working file name; use a non-sensitive label for your project. Your document references and observations, or leave missing evidence marked unknown.
Leave with
Premises-to-income-and-expense bridge with editable, expandable records and document locators Two fictional worked rows showing mismatches and decisions to review CSV and readable text exports with row provenance, method sources and edition A separate document-request companion with suggested reviewers

Edition 2026-09-30.1

Evidence and scope

Follow each claim to its source.

Tax Assessor

City of Providence, Rhode Island · Checked 2026-09-30

Assessor record responsibilities and official property-lookup path.

  • Providence-only example; no individual parcel record, rent roll or legal-use file was examined.
Open original source ↗